New Foreclosure Protections Established to Help Prevent Crisis
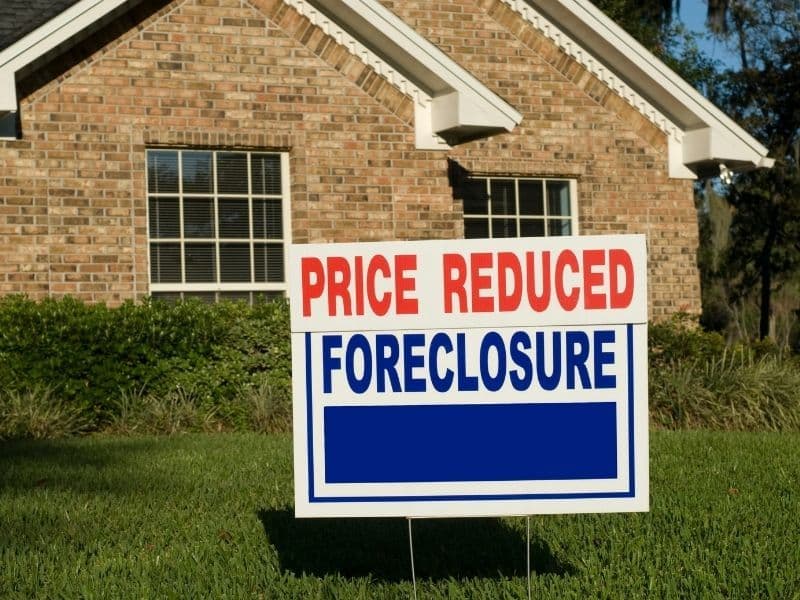
The CFPB continues its role of mitigating a possible housing catastrophe as foreclosure moratoriums end while the pandemic lingers.
Role of the CFPB During the Pandemic
The Consumer Financial Protection Bureau (CFPB) came to be when the dust settled after the housing crisis of 2008. It’s role of protecting consumers during a crisis was tested when a global pandemic decimated jobs and millions of American homeowners lost income and stopped making house payments. New rules set to take effect August 31, 2021, according to the CFPB website are to ensure a “smooth and orderly transition”.
Another foreclosure crisis could be worse than the late 2000’s. The CFPB under both the Trump and Biden administrations took dramatic steps to prevent delinquent homeowners from entering foreclosure when COVID-19 shut down the economy. Forbearance directives permit affected homeowners to temporarily stop making payments while the economy recovers. Nearly 1 million homeowners are expected to see their forbearance agreements expire by the end of 2021.
The new rules will make life easier for homeowners who meet certain criteria.
Servicer Requirements
The point of implementing the new CFPB rules is to require mortgage servicers to better communicate and work with homeowners to get mortgage payers back on track. Servicers must allow homeowners to consider their options and cannot immediately begin foreclosure proceedings once forbearance periods end.
When borrowers exit forbearance, the new rules will provide at least three options:
Source: consumerfinance.gov
- Resume regular mortgage payments.
- Lower their monthly mortgage payments.
- Sell their homes.
Resume Regular Mortgage Payments
The easiest and most “normal” option homeowners have is to simply resume their mortgage payments as-is. The payments missed while in forbearance are tacked onto the end of the term. While deferring these payments adds to your loan balance and may impact the interest you pay over time, most home loans never see maturity, so the effective impact is negligible.
Resuming your mortgage payments doesn’t change your payment or interest rate. You’ll begin making payments like you did pre pandemic and continue to do so as long as you own the home or until your loan is paid off.
Lower Their Monthly Mortgage Payments
Some homeowners whose income or financial situation hasn’t fully recovered will not be able to resume their regular mortgage payments. However, they may be in a position to handle a modified payment.
Loan modifications take an existing mortgage loan and generally improve the terms. Modifications can change one or more of the following:
- Interest Rate
Lowering the interest rate will reduce the monthly payment accordingly. Many homeowners already have a historically low mortgage rate, so decreasing the interest rate might not have a large enough impact on its own. - Loan Term
Extending a mortgage term will also lower the monthly payment. The impact depends on the remaining term prior to the modification. If a 30-year mortgage is relatively new, extending the length of the mortgage out to a new 30-year term won’t lower the payment much. - Principal Balance
If changing your rate and term isn’t enough, reducing your mortgage balance may have the greatest impact on your monthly payment. However, as you might expect, mortgage servicers may be reluctant to apply a principal reduction to your mortgage.
Combining two or more of the modifications above may be enough to satisfy a mortgage servicer and allow the homeowner to stay in the home. However, if an adequate loan modification cannot be reached, selling the home may be the last option to avoid foreclosure.
Sell Their Home
Home prices have appreciated dramatically over the last few years. While forbearance takes a toll on homeowner equity, selling your home could result in a mortgage that is paid off and possibly some cash in your pocket. Selling might not be ideal, but it will remove the threat of foreclosure and might provide enough cash back to get things back on track.
Exceptions to CFPB Rules Preventing Foreclosure
The CFPB rules are intended for well intentioned homeowners who genuinely want to stay in their home that were maintaining their mortgage prior to the coronavirus pandemic. Foreclosure proceedings can begin if the homeowner was more than 120 days delinquent before March 1, 2020.
Additionally, if the homeowner is more than 120 days delinquent and within the last 90 days has not responded to servicer requests to address the situation, the servicer may begin foreclosure proceedings.
If the homeowner has left or abandoned the home, foreclosure can begin.
Finally, if all other options have been exhausted to avoid foreclosure, the servicer may proceed.
For more information, please refer to the CFPB official website.